


 How Much Down Payment Do You Need as a First-Time Buyer with No Credit?
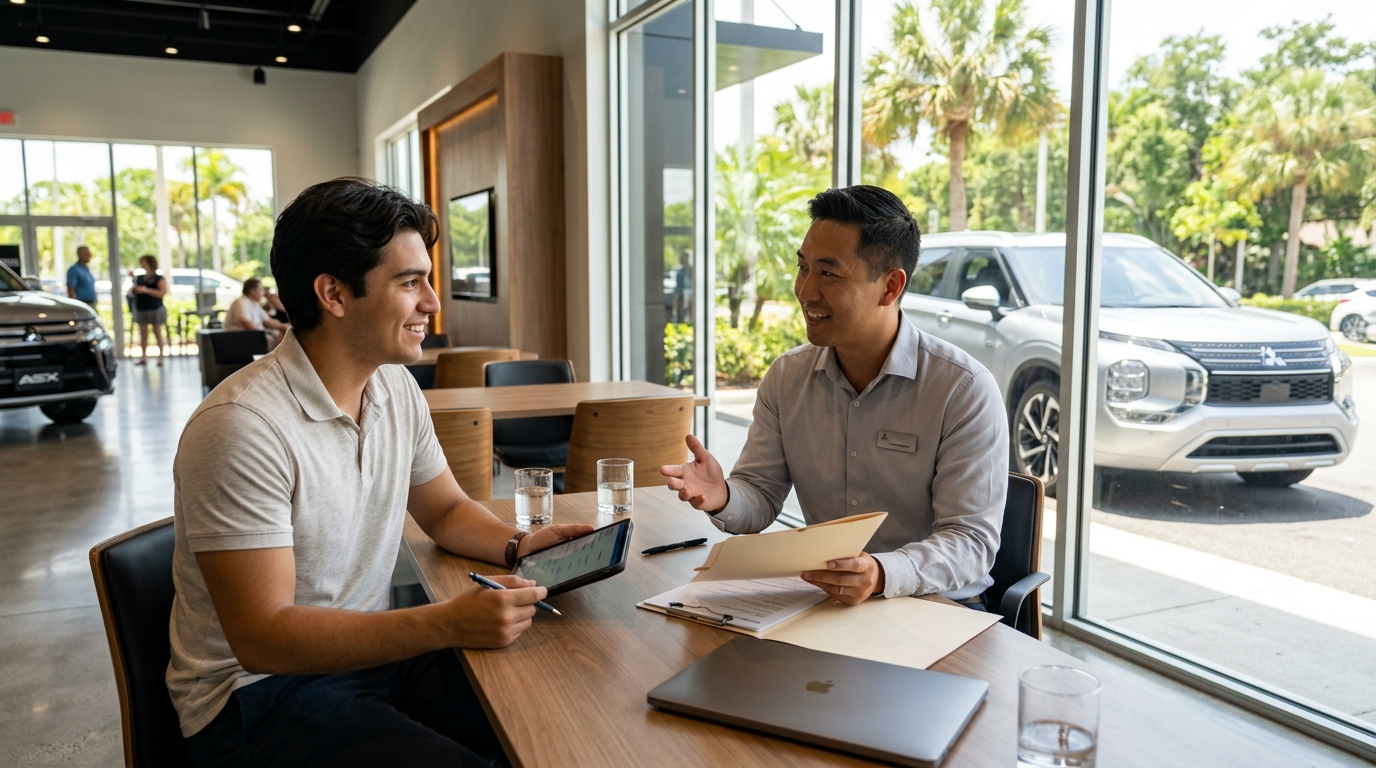
Most first-time car buyers with no credit history should speak with our finance team about down payment options based on their individual situation. Placing cash down lowers lender risk, reduces monthly payments, and satisfies underwriting guidelines that may influence lender review. Lenders evaluating a thin credit file focus heavily on risk management, and a cash down payment may help lower the amount financed and the monthly payment. Gathering your upfront capital before visiting our showroom at 8350 Park Blvd, Seminole, FL 33777 helps lock in loan approval terms without unexpected delays.
Start your simple online application today by completing our digital credit application to see how different down payment amounts adjust your loan structure. You can also give our finance desk (727) 435-1654 a call directly to talk through your options. For buyers who want to test drive vehicles in person, getting directions to St. Pete Mitsubishi puts you on the right path to starting your purchase with complete clarity.
Table of Contents
- Can You Get Approved for an Auto Loan with No Credit History?
- Why Getting Pre-Approved Before Shopping Sets You Up for Success
- What Documents Do Lenders Need to Verify Income and Residence?
- The 7 Steps to Getting Approved for Your First Vehicle
- How Long Does It Take to Build a Strong Credit Score with On-Time Payments?
- Finding the Right Fuel-Efficient Mitsubishi at St. Pete Mitsubishi
Can You Get Approved for an Auto Loan with No Credit History?
Yes, first-time car buyers can get approved for an auto loan with zero credit history because specialized auto financing programs evaluate income stability, employment tenure, and debt ratios rather than relying solely on a credit score.
A missing credit score is an underwriting challenge rather than a deal-breaker. Standard automated scoring algorithms struggle to price a blank file, which is why first-time applications are submitted to specialized lenders who review files manually. Underwriters look for a minimum gross monthly income between $1,500 and $2,000 from a single verifiable source, along with at least six to twelve consecutive months at your current job. Meeting these income thresholds proves your capability to handle monthly installments even without past credit references.
Choosing the right vehicle inventory also impacts approval speed. Subprime and first-time buyer underwriting guidelines favor sensible vehicles with strong resale value. Exploring our full lineup of pre-owned inventory allows buyers to secure a lower overall principal balance, which naturally fits within strict debt-to-income limits. Applicants navigating thin files can also utilize dedicated bad credit and no-credit financing solutions tailored to match individual income profiles.
Why Getting Pre-Approved Before Shopping Sets You Up for Success
Getting pre-approved before visiting a dealership establishes an exact vehicle budget, locks in a competitive interest rate baseline, and prevents buyers from overextending their monthly finances.
Pre-approval involves a soft credit review and preliminary income audit that yields a formal loan ceiling and estimated annual percentage rate. First-time buyers in Pinellas Park who commute daily along US 19 benefit immensely from establishing this financial benchmark early. Knowing your upper loan limit prevents falling in love with a vehicle outside your comfort zone and streamlines the buying experience into a stress-free vehicle selection process.
Shopping with a pre-approval in hand also maximizes your negotiating position. You can browse our selection of new vehicles knowing precisely how the principal translates to monthly payments. If you currently own an older vehicle, our team can help you value your trade-in to apply existing vehicle equity directly toward your down payment requirement.
What Documents Do Lenders Need to Verify Income and Residence?
Lenders require government identification, proof of steady income, proof of residence, vehicle insurance verification, and a list of personal references to approve auto financing for a buyer without established credit.
Preparing documentation prior to visiting the showroom prevents approval bottlenecks. For income verification, lenders expect two to three recent consecutive pay stubs showing year-to-date earnings, or W-2 forms and official tax returns if you are self-employed. Gig economy workers can supply three consecutive months of complete bank statements reflecting regular deposits. Income from unearned sources such as disability or court-ordered support qualifies as long as official benefit statements show ongoing eligibility for at least three future years.
Residency and reference checks verify personal stability. Proof of address typically requires a utility bill, lease agreement, or bank statement dated within the last 60 days showing your current address where you have resided for at least 12 continuous months. Lenders also request three to eight personal references with confirmed phone numbers and current addresses. Presenting a complete, organized paperwork folder allows finance managers to submit your file directly to underwriters for immediate verification.
The 7 Steps to Getting Approved for Your First Vehicle
Securing first-time car financing requires seven structured steps: check your credit report, set a budget using the 15% income rule, save a cash down payment, gather verification documents, secure pre-approval, select an appropriate vehicle, and complete final contract review.
First-time buyers walking into our finance office usually ask whether having zero credit history means an automatic denial before they even ask about interest rates. Following a systematic process eliminates that anxiety:
- Step 1: Check your credit profile through free bureau reports to confirm no fraudulent accounts or unexpected errors exist on your file.
- Step 2: Establish a total monthly vehicle budget where payments, fuel, and insurance remain at or below 15% to 20% of your gross monthly earnings.
- Step 3: Save between $1,000 and $2,500 for a cash down payment to lower the loan principal and satisfy lender underwriting limits.
- Step 4: Organize physical copies of your pay stubs, proof of residence, government photo ID, driver's license, and personal references.
- Step 5: Complete pre-approval applications within a 14-day window to protect your credit profile from multiple hard inquiries counting separately.
- Step 6: Pick a dependable vehicle that matches your daily driving requirements without exceeding your approved financing threshold.
- Step 7: Review the final retail installment contract to verify annual percentage rate, loan term length, and total finance charges before signing.
During vehicle selection, evaluating loan structures is essential. Comparing options between traditional auto financing and leasing programs ensures you select an ownership model that fits your long-term goals and mileage expectations.
How Long Does It Take to Build a Strong Credit Score with On-Time Payments?
Establishing 6 to 12 consecutive months of on-time auto loan payments creates a solid credit score in the mid-600s to low-700s for a first-time buyer with no prior file.
Auto loans are installment credit accounts, which represent one of the most impactful credit-building tools available. Each monthly payment is reported directly to the major credit reporting bureaus. As you make uninterrupted payments, your credit report develops a verifiable history of payment reliability and debt management.
After maintaining clean payment records for 12 months, your upgraded credit tier opens up future refinancing opportunities. Refinancing an initial first-time buyer auto loan after one year of consistent payments can secure lower annual percentage rates, dropping your monthly obligation and saving thousands in overall interest over the remaining term.
Finding the Right Fuel-Efficient Mitsubishi at St. Pete Mitsubishi
Choosing a reliable, fuel-efficient vehicle like a Mitsubishi Mirage or Mitsubishi Outlander Sport provides first-time buyers with long-term financial predictability backed by industry-leading warranty coverage.
Selecting an efficient model is the final piece of a smart car-buying strategy. Daily commuters in Clearwater navigating coastal highway routes benefit from the exceptional efficiency of the Mitsubishi Mirage, which delivers up to 36 mpg city / 43 mpg highway. Furthermore, every new Mitsubishi comes backed by a 10-year/100,000-mile powertrain limited warranty, protecting first-time owners from unexpected mechanical costs while building credit.
Our team makes acquiring your first vehicle straightforward and transparent. Eligible corporate employees, military personnel, and university graduates can take advantage of our Mitsubishi VIP purchase benefits to maximize savings. When you are ready to test drive, obtain directions to our showroom or reach out to our finance desk by calling (727) 435-1654 to finalize your approval today.
Keep Your Vehicle Running Strong
Keep your vehicle performing at its best with our service team:
© 2026 St. Pete Mitsubishi. All rights reserved.